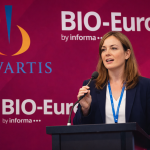
At the 2025 BIO Europe Summit, David Lowe, CEO of Ipsen, and Jeremy Levin, Chairman Emeritus of BIO, explored the seismic geopolitical and economic shifts currently reshaping the global life sciences landscape. The discussion detailed a new world defined by aggressive U.S. pricing reforms, the rapid ascent of Chinese innovation, and a critical inflection point for European biopharma. Industry experts characterized the current environment not as a temporary disruption, but as a fundamental transformation requiring a total revamp of commercial and clinical strategies.

The Erosion of Transatlantic Pricing Parity
The central challenge facing the industry stems from a radical rebalancing of global drug pricing, catalyzed by recent U.S. policy mandates. The panel indicated that the White House has moved beyond rhetoric, issuing formal directives to major pharmaceutical executives to address the disparity where the U.S. bears a disproportionate share of global R&D costs. Currently, net prices for innovative drugs in the U.S. are often three to four times higher than those in European markets. To close this gap, the U.S. is implementing most-favored-nation (MFN) clauses for Medicaid, pegging domestic prices to a basket of international markets, including the Big Five EU nations, Switzerland, Denmark, and Japan.
This shift fundamentally threatens the traditional launch-and-license model used by smaller biotechs. Experts suggested that if a biotech launches in the U.S. and then licenses the drug to a European distributor who accepts a significantly lower price, that lower price could catch the company in the U.S. through MFN triggers. The discussion underscored that for new launches, Europe will likely be forced to accept higher price points to maintain access to cutting-edge therapies, potentially ending the era of deep discounts for the continent’s healthcare systems.
China’s Rise and the Shift in Therapeutic Focus
While the U.S. retools its economic levers, China is executing a multi-decade strategic plan to dominate health care innovation. The panel noted that the volume of Investigational New Drug (IND) filings at the FDA is shifting, with one-third now originating from Chinese developers. However, this growth is not uniform across all specialties. In 2010, oncology represented roughly 25% to 30% of research dollars; by 2020, that figure surged to 60%. Panelists warned that China is positioned to sweep the oncology space with incremental innovations, such as hundreds of new PD-1 variants, making the sector increasingly crowded and difficult for Western investors.
In response, the discussion highlighted a critical need for biopharmas to pivot toward underserved therapeutic areas where true potential for breakthrough returns remains high. These include neurology, psychiatry, cardiology, and pulmonology. Alnylam’s success was cited as a 20-year journey driven by a persistent vision to transform a disease area—specifically RNAi therapeutics—rather than following the herd into saturated markets. Experts emphasized that leadership in this era requires the foresight to invest in fundamental biology that addresses the 75% of mortality causes outside of cancer.
Strategic Solutions for a Resilient European Ecosystem
To prevent European patients from being left in the rain, the panel proposed several structural reforms to accelerate the translation of science into medicine. A primary concern is the current incentive structure for European academia, where performance is often measured by publications rather than clinical translation. One proposed solution is to shift university funding models so that research labs rely more on royalty streams from commercialized inventions, fostering a more entrepreneurial mindset among professors.
Furthermore, the discussion called for an urgent pension fund revolution in Europe. Drawing a comparison to Australia—which seen a massive explosion in innovation after allowing national pension funds to invest more aggressively in domestic innovative companies—panelists argued that European capital markets must be unblocked. Currently, European venture capital is dwarfed by U.S. levels by a factor of roughly 20 to 1. By incentivizing or mandating a small percentage of European pension funds to allocate to high-growth biotechs, the continent could create a self-sustaining cycle of wealth and job creation.
Future Outlook: From Cost Center to Value Generator
The future of the industry depends on a fundamental shift in how medicine is perceived by the public and policymakers. The panel concluded that biopharma has allowed itself to become a piñata for populist politicians, largely due to a failure in communication. Experts advocated a direct-to-population educational campaign in Europe to reframe innovative medicine as a value generator rather than merely a cost. They noted that while governments often squeeze drug budgets, they simultaneously spend billions on less impactful public works; for instance, subsidies for a single Swiss cow can exceed the annual per-capita spend on cancer drugs.
As the FDA faces potential long-term damage and regulatory uncertainty in the U.S., Europe has a unique window to build an independent, robust regulatory and capital framework. The consensus among leaders is that the current tsunami of change is an opportunity to excise redundancies—such as the overlapping layers of the EU HTA regulation—and streamline clinical trials. By leveraging its base of 500 million citizens and its world-class fundamental science, Europe can transition from being a dependent observer to a primary engine of global healthcare transformation.

Moe Alsumidaie is Chief Editor of The Clinical Trial Vanguard. Moe holds decades of experience in the clinical trials industry. Moe also serves as Head of Research at CliniBiz and Chief Data Scientist at Annex Clinical Corporation.